 BeeHome Collective · VA Loan Education
2025 VA Guidelines · Plain English
Your VA Loan,
Explained.
No jargon. No confusion. Just your benefit, clearly explained.
You earned this benefit through your service. This page explains exactly how it works, what the terms mean, and how to use it — in plain English, with no jargon. When you're ready, Amy will take it from there.
What Is a VA Loan?
A VA loanA mortgage loan backed by the U.S. Department of Veterans Affairs. The VA guarantees part of the loan, which lets lenders offer better terms. is a home mortgage benefit earned through military service. It's backed by the U.S. Department of Veterans Affairs and offered through approved private lenders — like NOVA Home Loans. Because the VA guaranteesThe VA's promise to repay the lender a portion of the loan if the borrower defaults. This reduces lender risk and allows better terms for the borrower. part of the loan, lenders can offer better terms than you'd get anywhere else.
Think of it as the government standing behind you at the closing table — reducing the lender's risk so you can access better rates, no down payment, and no mortgage insurance. It is, without question, the most powerful home financing benefit available to any American.
"The VA loan isn't just a mortgage product. It's a thank-you. It exists specifically to help the people who served this country build wealth and stability through homeownership."
The 6 Big Benefits.
No other loan program combines all of these. This is what makes the VA loan exceptional.
Qualified buyers can purchase a home with zero down payment. You may choose to put money down — and sometimes that makes strategic sense — but you are never required to. This is the single biggest financial advantage the VA loan provides.
Private Mortgage Insurance (PMI)A monthly fee charged by lenders when you put less than 20% down on a conventional loan. PMI protects the lender, not you — and can add $100–$400/month to your payment. is required on conventional loans when your down payment is under 20%. VA loans never require PMI, regardless of your down payment. This alone can save you $150–$400 per month.
Because the VA guarantees a portion of the loan, lenders take on less risk — and they pass those savings to you in the form of lower interest ratesThe percentage of your loan amount charged annually by the lender for borrowing money. VA rates are typically 0.25%–0.5% lower than comparable conventional rates.. VA rates are typically among the lowest available for any loan type.
Your VA benefit isn't a one-time deal. After selling your home and paying off the VA loan, your entitlementThe dollar amount the VA will guarantee on your loan. Full entitlement means no loan limit. Partial entitlement may remain after a previous VA loan. is restored and you can use it again — on your next PCS, your next home, or whenever you're ready.
Many veterans don't realize they can carry two VA loans simultaneously. If you still have a VA loan on your current home — say, you PCS'd and are renting it out — you may have enough bonus entitlementAlso called second-tier or additional entitlement. The VA guarantees up to 25% of the conforming loan limit ($766,550 in 2025 = $191,637.50 in bonus entitlement). This is what allows two VA loans at once. (also called second-tier entitlementThe remaining VA guarantee available after your first VA loan is counted. As long as your remaining entitlement covers 25% of the new loan, you may not need a down payment.) remaining to purchase your next home with no down payment. This is one of the most underused and misunderstood advantages of the VA loan — and Amy can calculate exactly how much entitlement you have left and whether you qualify for a second VA loan without selling your first home.
The VA itself has no official minimum credit scoreA numerical score (300–850) representing your creditworthiness. Higher scores mean better rates and easier approval. Most VA lenders require 580–620 minimum. requirement. Lenders set their own minimums — NOVA typically requires 580+. VA loans are significantly more accessible for borrowers with credit challenges than conventional or FHA alternatives.
The VA limits what you can be charged at closing. Non-allowable feesFees the VA prohibits lenders from charging to the veteran buyer. These costs must be paid by the seller or lender instead. — like attorney fees, brokerage fees, and prepayment penalties — cannot be passed to the buyer. This protects you from being nickel-and-dimed at the table.
Who Is Eligible for a VA Loan?
Eligibility is based on your military service history. If you fall into one of these categories, you likely qualify. Amy will verify your specific status when you start the process.
Served on active duty and were discharged under conditions other than dishonorable. Minimum service requirements vary by era — most require 90 days active wartime service or 181 days peacetime service.
Currently serving with at least 90 continuous days of active duty. PCS ordersPermanent Change of Station — official military orders relocating a service member to a new duty station. VA loans can be used to purchase at the new duty station location. to a new duty station? You can use your VA loan to buy at your new location.
Members with 6 years of service in the Selected Reserve or National Guard, or 90 days of active duty service under Title 10. 2020 legislation expanded eligibility significantly for Guard and Reserve members.
Unremarried surviving spouses of veterans who died in service or from a service-connected disability. Also eligible: spouses of service members listed as MIA or POW. Remarried spouses may also qualify in some circumstances.
Officers of the Public Health Service and National Oceanic and Atmospheric Administration (NOAA) may qualify under specific service conditions.
Amy will determine your eligibility and obtain your Certificate of Eligibility (COE)The official VA document that confirms your eligibility for the VA loan benefit and shows your available entitlement amount. for you — at no cost, within minutes, as part of starting your loan process.
You don't need to figure out your eligibility on your own. Amy will determine your qualification status, pull your Certificate of Eligibility directly through VA systems, and walk you through exactly what it means for your purchase.
VA Entitlement — Explained Simply.
EntitlementThe dollar amount the VA guarantees to the lender on your behalf. Full entitlement = no loan limit. Remaining entitlement = what's available after a previous VA loan. is the amount the VA will guarantee on your behalf — essentially, the VA's commitment to the lender. Understanding entitlement is what allows you to use your VA benefit multiple times, and even have two VA loans at once in certain situations.
If you've never used your VA loan benefit — or you've used it and fully paid off the previous loan and disposed of the property — you have full entitlement. This means:
If you have an active VA loan or previously used your benefit without fully restoring it, you have remaining entitlement. You may still be able to use the VA loan again — but loan limits may apply depending on your county.
When you sell your VA-financed home and pay off the loan in full, your entitlement is restoredThe process of returning your VA entitlement to its full amount after a previous VA loan is paid off, allowing you to use the full benefit again on a future purchase. automatically — meaning your next purchase has all the same benefits as your first. You can request a one-time restoration even without selling, in certain circumstances.
Calculating remaining entitlement and understanding how to use it across multiple properties can get complex — especially across several PCS moves. Amy will calculate your remaining entitlement, explain exactly what it means for your buying power, and restore your eligibility after a sale when applicable. You don't have to figure this out alone.
Certificate of Eligibility (COE).
Your Certificate of Eligibility (COE)The official document issued by the VA that confirms you are eligible for the VA home loan benefit and shows the entitlement amount available to you. is the official document that proves you qualify for the VA loan benefit. It tells the lender how much entitlementThe dollar amount the VA guarantees to the lender. More entitlement = more buying power without a down payment. you have available and confirms your military service status.
Most borrowers think getting their COE is complicated. It's not — when you have the right lender. The VA has an online portal that allows approved lenders to pull your COE instantly in most cases.
In most cases, all Amy needs is your name, Social Security number, and date of birth to pull your COE instantly through the VA lender portal. Documents may be required in certain situations:
Amy will obtain your Certificate of Eligibility directly through the VA's lender portal — at no cost to you, as part of starting your loan process. In most cases this happens instantly. If manual review is needed, she'll guide you through exactly what documents to gather.
The VA Funding Fee.
The VA funding feeA one-time fee paid to the VA that helps fund the loan guarantee program. It can be financed into the loan amount so you don't pay it out of pocket at closing. is a one-time fee charged by the VA that helps fund the entire loan guarantee program — keeping it available for future veterans. It's the trade-off for having no PMI and no down payment requirement.
The good news: it can be financedRolled into your loan amount instead of paid at closing. If you finance the funding fee, it slightly increases your loan balance and monthly payment. directly into your loan — so you don't pay it out of pocket at closing. And some veterans are completely exempt.
| Loan Use | Down Payment | First Use | Subsequent Use |
|---|---|---|---|
| Purchase / Construction | Less than 5% | 2.15% | 3.30% |
| Purchase / Construction | 5% – 9.99% | 1.50% | 1.50% |
| Purchase / Construction | 10% or more | 1.25% | 1.25% |
| VA IRRRL Refinance | N/A | 0.50% | |
| Cash-Out Refinance | N/A | 2.15% | 3.30% |
You may be exempt from the funding fee entirely if you:
The VA Loan Process.
Here's how a VA home purchase works from start to keys in hand. Amy handles the lending side at every step — you focus on finding the home you love.
Amy pulls your COECertificate of Eligibility — the VA-issued document confirming you qualify for the VA loan benefit. directly through the VA lender portal. Takes minutes in most cases. This confirms your eligibility and entitlement amount.
Amy reviews your income, assets, debt-to-income ratio (DTI)Your total monthly debt payments divided by your gross monthly income. VA generally allows up to 41%, though exceptions exist with compensating factors., and credit to issue a pre-approval letter. This is your shopping credential — it tells sellers you're serious and qualified.
Work with a VA-savvy Realtor (Amy can connect you with one) to find a home that meets VA Minimum Property Requirements (MPRs)VA-required property standards ensuring the home is safe, structurally sound, and sanitary. A VA appraiser reviews these during the appraisal.. The home must be your primary residence.
A VA-approved appraiserA licensed professional who assesses the fair market value of the property and reviews it against VA Minimum Property Requirements. visits the property to confirm its market value and that it meets MPRs. The VA appraisal is not a home inspection — always get a separate inspection too.
UnderwritingThe lender's process of verifying all your financial information and the property details before approving the loan for funding. is where NOVA's team reviews your full file — income, assets, credit, appraisal — and issues the loan approvalThe lender's formal decision to fund the loan, typically with conditions that must be satisfied before closing.. NOVA uses in-house underwriting, which means faster decisions and fewer surprises.
You sign your loan documents, any remaining closing costsFees and expenses paid at the time of closing. VA limits what veterans can be charged. Typical VA closing costs are 1–3% of the loan amount. are settled, and the keys are yours. Bring your government-issued ID — and your Power of Attorney if your spouse will be signing on your behalf.
The VA IRRRL — Your Rate Reduction Shortcut.
If you already have a VA loan and rates have dropped, the Interest Rate Reduction Refinance Loan (IRRRL)Also called the VA Streamline Refinance. Allows existing VA borrowers to lower their rate with minimal documentation — no appraisal or income verification required in most cases. — also called the VA Streamline Refinance — is one of the easiest refinances available to any homeowner.
"The IRRRL isn't just about getting a lower rate — it's about using it at exactly the right moment for your unique financial situation. I'll walk you through the timing, the break-even point, and every option available so the refinance works hardest for you, not just on paper."
VA Loan Glossary.
Real estate has its own language. Here are the terms you'll hear most often in a VA home purchase — explained the way a friend would explain them.
A professional assessment of a home's fair market value, conducted by a VA-approved appraiser. Required for every VA purchase. The VA will not lend more than the appraised value.
A monthly, tax-free housing stipend paid to service members not living in government housing. BAH is based on your pay grade and duty station zip code — and lenders can use it to qualify you for a larger loan.
The official VA document confirming your eligibility and showing your available entitlement. Amy pulls this directly through the VA portal — you don't have to request it yourself.
Fees and expenses paid at closing — title insurance, recording fees, prepaid interest, etc. VA limits what veterans can be charged. Sellers can pay all of your closing costs.
Your monthly debt payments divided by your gross monthly income. VA generally allows up to 41%, but exceptions exist. The lower your DTI, the stronger your application.
The amount the VA guarantees on your behalf. Full entitlement = no loan limit. Partial/remaining entitlement applies when you've used the benefit before without full restoration.
A neutral third party that holds funds and documents during the transaction. Your monthly payment includes an escrow portion that the lender holds to pay property taxes and insurance on your behalf.
A one-time VA fee (1.25%–3.30%) that funds the loan guarantee program. Can be financed into the loan. Veterans with service-connected disabilities of 10%+ are exempt.
Interest Rate Reduction Refinance Loan — a simplified refinance for existing VA borrowers. Minimal documentation, no appraisal in most cases, low 0.50% funding fee.
Your loan amount divided by the home's appraised value. A $0 down VA loan has a 100% LTV. VA doesn't require PMI even at 100% LTV — a major advantage.
VA standards that a property must meet to qualify for a VA loan. The home must be safe, structurally sound, and sanitary. The VA appraiser checks these — it's not a full home inspection.
A lender's written commitment to fund your loan up to a specified amount, based on a review of your financials. A pre-approval letter from Amy tells sellers you are serious, qualified, and ready.
The home you intend to live in as your main dwelling. VA loans are for primary residences only — not investment properties. However, you can rent your VA-financed home after moving out.
A condition the VA has determined was caused or worsened by military service. Even a 10% disability rating exempts you from the VA funding fee — potentially saving thousands.
Insurance protecting against claims on the ownership of your property from past events. Lender's title insurance is required. Owner's title insurance is optional but recommended.
Another qualified buyer taking over your VA loan — including your original interest rate. If you locked in a low rate, your loan could be assumed by the buyer when you sell, making your home highly attractive.
Start Your VA Loan with Amy.
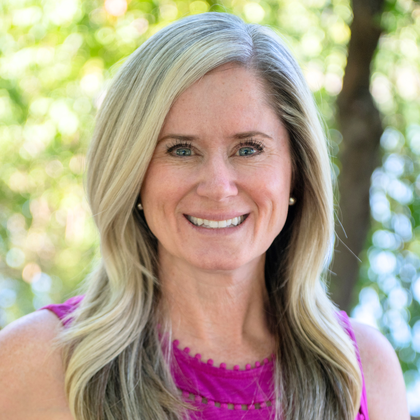
"Wherever the military sends you next, I'm licensed and ready. Let me handle the paperwork — you focus on finding home."
As an Army spouse of 32 years and an Army Mom, Amy has lived the PCS lifestyle and understands exactly what military families need when it comes to home financing. She is licensed in WA, CA, AZ, and FL — the states where military families most often land — and specializes exclusively in the loan types that serve veterans and military families best.
Amy will personally: Obtain your COE · Calculate your remaining entitlement · Restore your eligibility after a sale · Connect you with a trusted VA-savvy Realtor · Guide you from pre-approval to keys in hand.
BeeHome Collective